This Week & Next: Inflation, AI-Anxiety, and Earnings
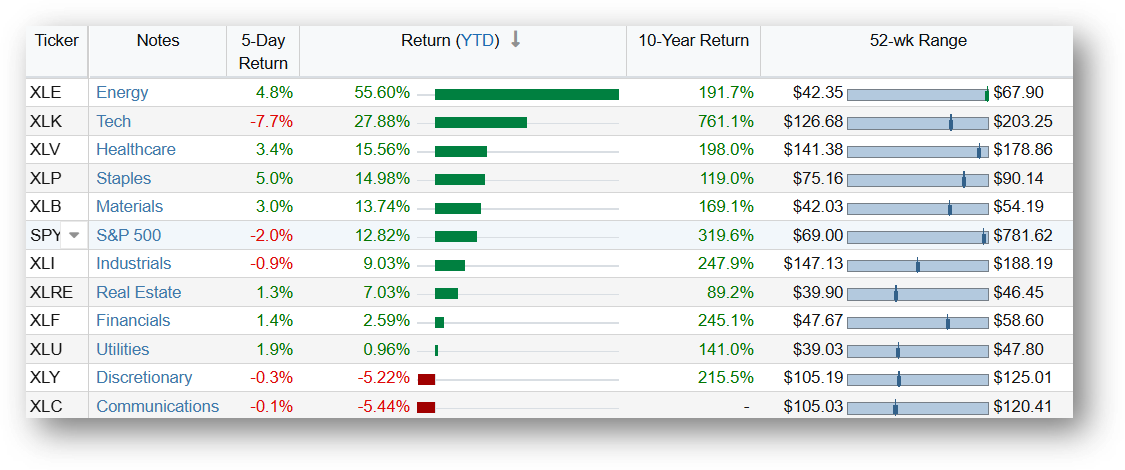
The market has a familiar problem: investors want growth, but they’re nervous about the cost. Stocks stumbled this past week (especially Tech, -7.7%) as enthusiasm is no longer enough. Investors need proof.
Five Cracks in the Dam
Stocks lost their footing. The S&P 500 (-2.0%) and Nasdaq (-4.5%) declined this past week as investors are getting cautious—particularly about AI.
Inflation has the Fed in a bind. A hotter headline inflation reading (3.7% yoy, up from 3.4% last month, and ahead of 3.6% forecasts) continues to complicate the outlook for interest rates. Persistent price pressures delay rate cuts and challenge stock valuations and hopes for cheaper borrowing.
AI stocks faced a reality check. Semiconductor and technology shares weakened as investors questioned whether massive AI spending will generate enough returns. It seems obvious the long-term opportunity remains compelling, but the near-term outlook is uncertain as investors increasingly want proof.
The VIX spiked amid hedge-fund blow-up rumors. On Friday, volatility spiked as speculation circulated about a major market participant potentially being forced to liquidate positions. The episode raised fears of a broader unwind. However, the identity of any fund involved—and whether a blow-up actually occurred—remained unconfirmed. Forced selling (from a liquidation) can quickly turn an ordinary pullback into something much more dangerous and opportunity creating.
Credit risk came into more focus. Concerns about CoreWeave’s big debt load highlighted another dangerous side of the AI boom: even when demand is real, financing it can be dangerous.
Five things to watch in the week ahead
Housing data arrives (Tuesday). Housing starts and building permits will offer a fresh look at the health of the U.S. housing market. Weakness could signal more economic strain, while resilience may also complicate the case for lower interest rates.
Wednesday Post-Market Earnings Will Test AI. Meta (Wed, post market) needs to show massive AI investments are translating into advertising growth and profits. Tesla (Wed, post market) faces questions about vehicle margins and autonomy. Texas Instruments (Wed, post market) offers clues about industrial chip demand, while Lam Research (Wed, post market) provides a read on semiconductor-equipment spending. IBM (Wed, post market) rounds out the picture, with investors watching enterprise AI adoption and software growth. Together, these earnings reports could determine whether the AI trade regains momentum—or faces another reality check.
The Treasury auctions $13 billion in 20-year bonds (Wed, 1:00 pm ET). Investors will watch demand for long-term government debt for clues about appetite for Treasuries and the yields the government must offer. A weak auction could push yields higher, adding pressure to growth stocks.
Jobless claims will test the labor market (Thurs, 8:30 am ET). Weekly initial jobless claims will provide a fresh read on layoffs. If claims remain low, it could reinforce the view that the economy is resilient—and give the Fed less reason to cut rates. A surprise jump could revive concerns about slowing employment.
Business activity and consumer sentiment (Fri) will provide an economic reality check. Specifically, the S&P Global Flash PMIs (9:45 am ET) and the University of Michigan’s final October Consumer Sentiment Index (10 am ET).
The Bottom Line
The market’s central question is shifting from How big can the AI opportunity become? to Who will turn that opportunity into durable profits—and at what price?
Earnings next week could provide answers, while economic data will help determine whether interest rates become a tailwind or another obstacle.
Market volatility and declines may provide more attractive entry points—within reason. Just don’t let the daily moves distract from your long-term goals.