
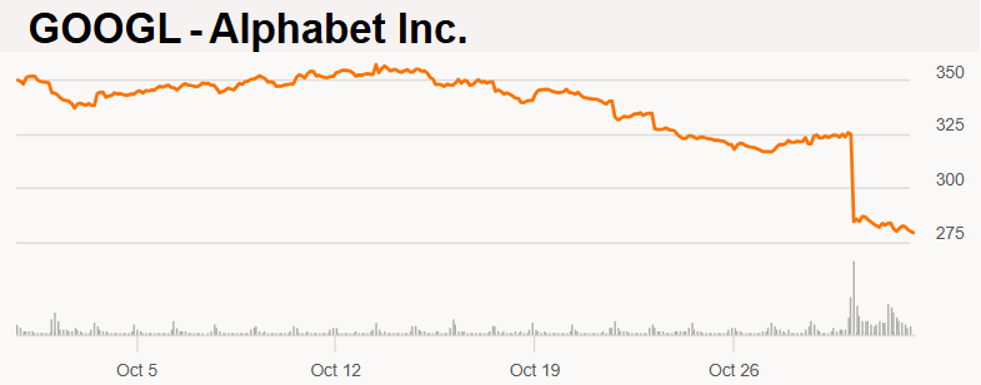
Alphabet (GOOGL) announced earnings this past week and the shares sold off hard. If you are a long-term investor—the selloff is a gift—consider buying more. Here are 5 reasons why…
1. Shortsighted Market Valuation
Near-term fear is driving the share price lower (Alphabet now trades at only 14.7x earnings), despite the fact that the company is extremely profitable and growing at an impressively high trajectory (and into a very large market opportunity—cloud and AI).
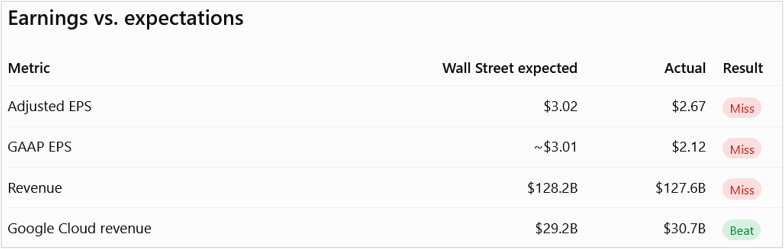
Specifically, the shares sold off because the company missed revenue and earnings targets (see table below), and because the market is overly fearful about near-term spending (the company reported $9.1B in negative free cash flow, and management warned 2027 capital expenditures will rise significantly).
But in reality, the near-term spending is a good thing—it means the company sees tremendous growth opportunities ahead—particularly in cloud and AI.
And to be clear, Google is growing rapidly. For example Q3 2026 revenue of $127.6B was up +25% year-over-year, and cloud revenue was even more impressive—growing 103% year-over-year to $30.7B.
2. Google Cloud is Impressive
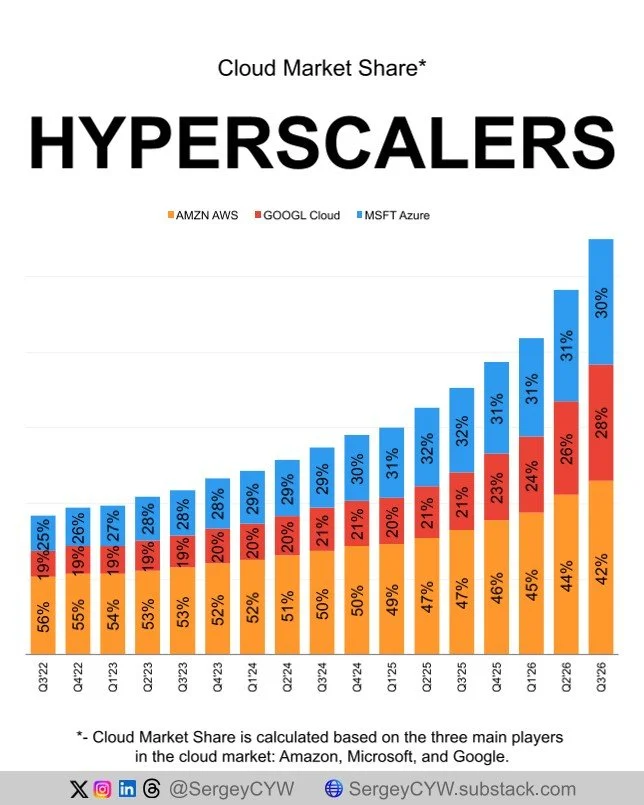
One of the big three cloud providers (behind only Amazon and Microsoft), Google Cloud significantly beat expectations (see table above) and revenue more-than-doubled year-over-year (+103%). Cloud is a clear bright spot and there is a lot of room for continued high growth (as evidenced by Alphabet’s impressive capex).
3. AI Fear is Overdone
Gemini positions Alphabet at the forefront of the global AI race. Yet fear about massive capex and negative free cash flow have investors panicking. And adding fuel to the fear fire, Google reported that search monetization is slowing (Google search revenue grew 12% in Q3 2026, down from 17% in Q2), while the company’s CFO acknowledged that AI Mode queries currently monetize less effectively than traditional search. The fear is that AI competitors are potentially taking both users and advertiser budgets from Alphabet.
Google is responding by expanding advertising inside AI overviews and AI mode, but AI still threatens how people search—and thereby causing Alphabet to potentially earn less money per search. This is the big risk many fearful investors are pricing in.
4. Massive Distribution is Underappreciated
With all the focus on how cloud and AI work, investors are forgetting the trillion pound gorilla in the room: Android, Chrome, YouTube and Google Workspace give Alphabet unparalleled global reach. This ecosystem is not something AI competitors can easily or rapidly displace.
5. Financial Strength
Alphabet has enormous cash generation, strong margins and substantial resources to fund AI investment, innovation and shareholder returns.
And trading at only 14.7x earnings, with a 0.4x forward PEG, and very high sales growth trajectory, Wall Street analysts continue to rate the shares a strong buy, as you can see in the table above (1=strong buy, 5= strong sell)—which also includes a list of other powerful growth and AI names down big over the last couple days).
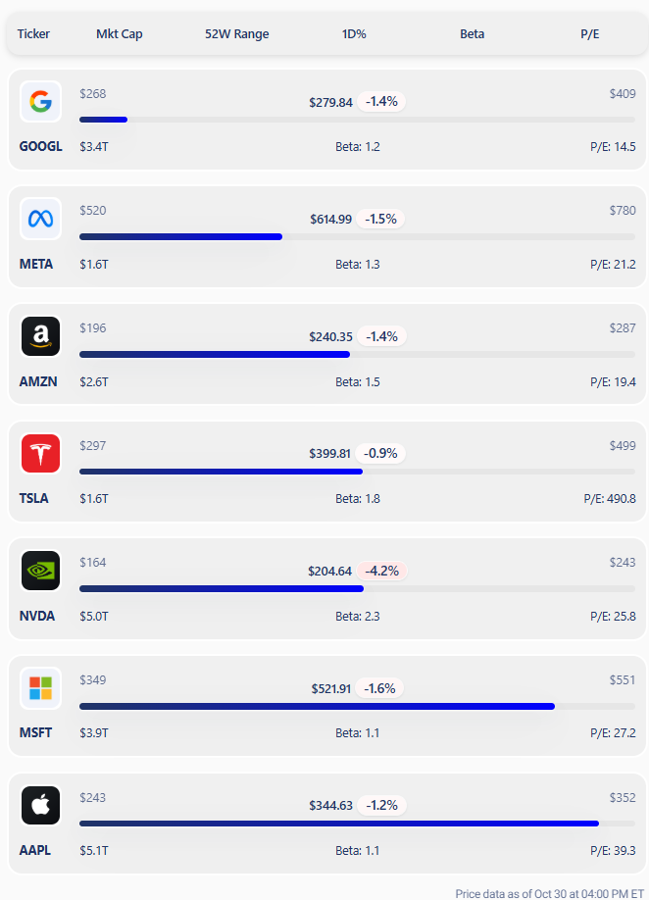
*(click the image for live data).
The Bottom Line
Alphabet combines dominant existing businesses with significant growth opportunities in AI and cloud computing, making it a compelling long-term investment. And the most recent fear and selloff makes the shares even more attractive for long-term investors. I am long Alphabet and may add to my position size from here.